Mortgage Refinance Calculator: Should You Refinance?

Quick answer
Refinancing makes sense when your monthly savings repay closing costs (usually 2% to 5% of the loan) before you move. For example, refinancing a $300,000 balance from 7.5% to 6.25% saves about $291 a month; with $6,000 in costs it breaks even in about 21 months. Watch out for restarting a long term, which can raise total interest.
Is it worth refinancing your mortgage? Our free refinance calculator shows your new payment, monthly savings, break-even month and how total interest changes, so you can decide with real numbers.
Also Explore
Mortgage Refinance Calculator
Compare your current loan with a new one and see your monthly savings and break-even point.
When does refinancing make sense?
- You can lower your rate enough that monthly savings repay closing costs well before you plan to move.
- You want to remove mortgage insurance, for example moving from FHA to conventional once you have 20% equity.
- You want a shorter term to pay the home off sooner.
- You want to switch from an adjustable rate to a fixed rate.
- You need cash for major repairs through a cash-out refinance (use with care).
The break-even point
Refinancing costs money, usually around 2% to 5% of the loan. Divide your closing costs by your monthly savings to find the break-even point. In the calculator example, a $300,000 balance at 7.5% with 28 years left, refinanced to 6.25% for 30 years, saves about $291 a month. With $6,000 in costs, it breaks even in about 21 months. If you plan to stay longer than that, the refinance likely pays off.

Watch out for restarting the clock
If you are 5 years into a 30-year loan and refinance into a new 30-year loan, you extend your payoff by 5 years. Your payment may drop, but total interest can still rise. To avoid this, choose a shorter term (like 20 or 15 years) or keep making your old payment amount on the new loan. See 15 vs 30-year mortgages.
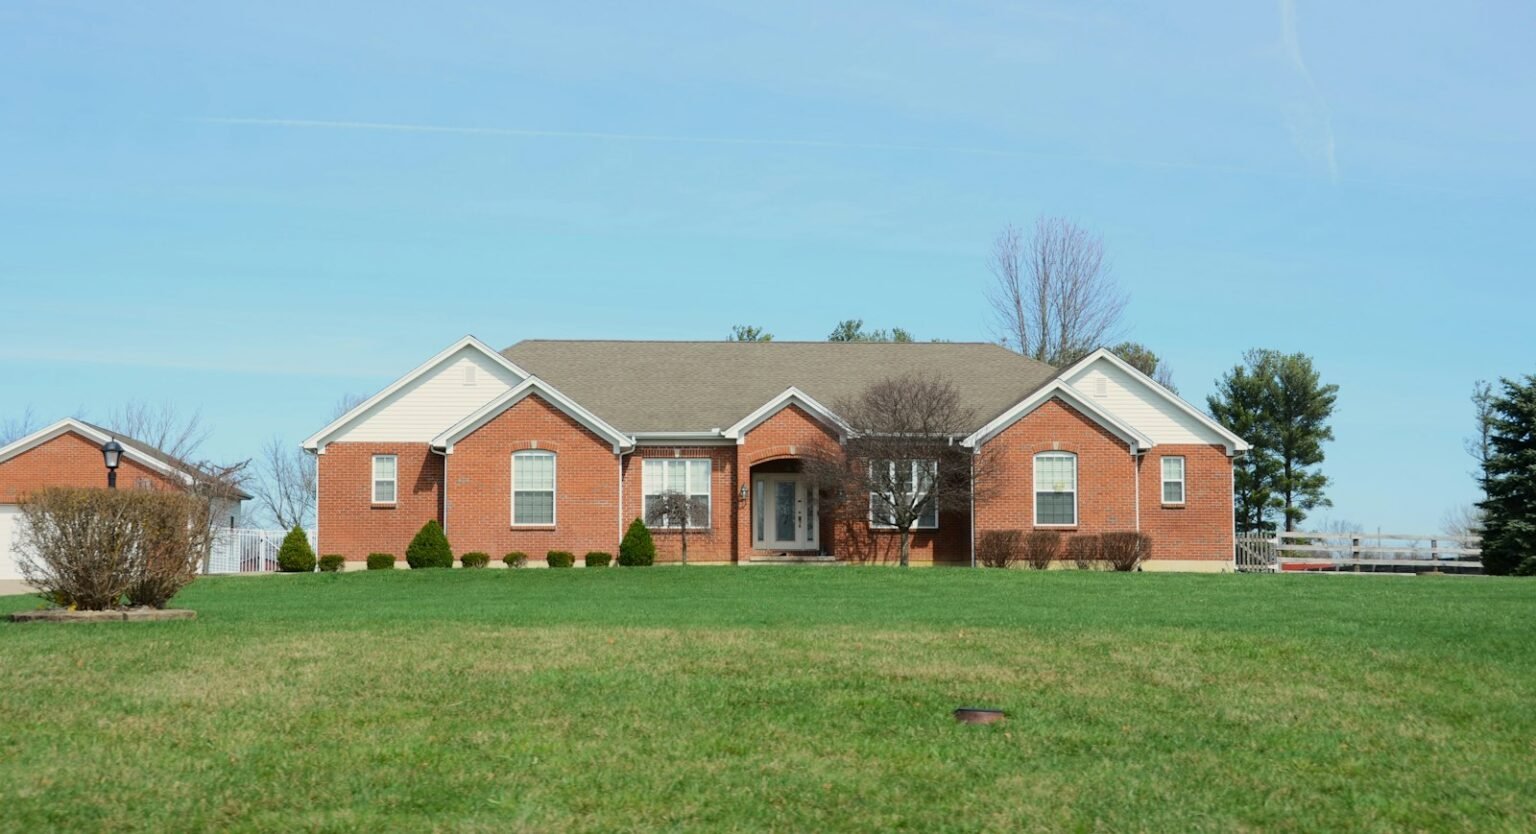
A refinance is worth it when you will stay in the home longer than the break-even point, and you are not just stretching out your debt.
Types of refinance
| Type | What it does | Best for |
|---|---|---|
| Rate-and-term | Changes the rate and/or term | Lower payment or faster payoff |
| Cash-out | Borrows more than you owe and gives you the difference | Large repairs or consolidating high-interest debt |
| Streamline (FHA, VA) | Simplified refinance with less paperwork | Existing FHA or VA borrowers |
| FHA to conventional | Moves to a loan without lifetime MIP | Owners with 20%+ equity and good credit |
How to refinance
- Check your credit score and home equity.
- Get Loan Estimates from at least three lenders.
- Compare rates, fees and the break-even point.
- Lock your rate when you are ready.
- Provide documents and schedule an appraisal if required.
- Review the Closing Disclosure and close.

Refinance checklist
- Monthly savings large enough?
- Break-even before you move?
- Not restarting a long term?
- Compare 3+ lenders.
- Check for prepayment penalties.
Refinance calculator examples: how much a lower rate saves
These examples use the same starting point as the calculator above: a $300,000 balance at 7.5% with 28 years left, a current principal and interest payment of about $2,139, and closing costs of $6,000 (2% of the loan). Each row shows a new 30-year loan at a different rate. Figures are rounded and cover principal and interest only.
| New rate (30 years) | New payment | Monthly savings | Break-even |
|---|---|---|---|
| 7.00% | about $1,996 | about $143 | about 42 months |
| 6.75% | about $1,946 | about $193 | about 31 months |
| 6.50% | about $1,896 | about $242 | about 25 months |
| 6.25% | about $1,847 | about $291 | about 21 months |
| 6.00% | about $1,799 | about $340 | about 18 months |
| 5.75% | about $1,751 | about $388 | about 16 months |
The pattern is clear: a half-point drop takes more than three years to pay back, while a drop of a point or more pays back in about two years or less. If you might sell or move within three years, a small rate drop is rarely worth it.
Shorter term vs lower payment: the total interest trade-off
A refinance calculator shows the monthly payment, but the bigger number is total interest. Using the same $300,000 balance and a 6.25% rate, here is how the term changes the picture (rounded, principal and interest only):
| Option | Monthly payment | Total interest over the loan |
|---|---|---|
| Keep current loan (7.5%, 28 years left) | about $2,139 | about $418,600 remaining |
| Refinance to 30 years at 6.25% | about $1,847 | about $365,000 |
| Refinance to 20 years at 6.25% | about $2,193 | about $226,300 |
| Refinance to 15 years at 6.25% | about $2,572 | about $163,000 |
The 20-year option costs only about $54 a month more than the current payment but cuts remaining interest by close to $192,000 and ends the loan 8 years sooner. That is often a better deal than the lowest possible payment. Compare the terms in our 15 vs 30-year mortgage guide.
The “keep paying the old amount” strategy
If you refinance to 30 years at 6.25% but keep paying your old $2,139 each month, the extra principal pays the loan off in about 21 years, with total interest of roughly $240,000. You keep the flexibility of the lower required payment if money gets tight, while still saving a lot of interest.
How to use this refinance calculator step by step
- Find your current balance and rate on your latest mortgage statement, not your original loan papers.
- Enter the years left on your current loan. If you are 5 years into a 30-year loan, enter 25.
- Enter a real quoted rate from a Loan Estimate, not an advertised rate, which may assume points or perfect credit.
- Pick the new term and try more than one: 30, 20 and 15 years.
- Enter total closing costs from the Loan Estimate, including lender fees, appraisal, title and any points.
- Read three numbers: monthly savings, break-even month and lifetime interest change. A good refinance usually looks good on all three.
What is in refinance closing costs
Closing costs usually run about 2% to 5% of the loan. Knowing the pieces helps you compare offers and spot fees you can shop for:
- Lender fees: origination, underwriting and processing.
- Discount points: optional upfront interest paid to lower the rate. Run the break-even math separately for points.
- Appraisal: often required, though some streamline refinances skip it.
- Title search and lender’s title insurance.
- Recording fees and government charges.
- Prepaid items: interest, property taxes and insurance for your new escrow account. These are not true fees, but they affect your cash to close.
A “no-closing-cost” refinance rolls the costs into a higher rate or a larger balance. That can make sense if you expect to move soon, but enter the higher rate in the calculator to compare honestly. See our closing cost calculator for estimates.
Common refinancing mistakes
- Comparing only monthly payments. A longer term can lower the payment and still raise total interest.
- Getting one quote. Rates and fees vary between lenders; get at least three Loan Estimates on the same day.
- Ignoring how long you will stay. If you move before the break-even month, the refinance loses money.
- Using cash-out for spending. Turning home equity into a vacation or car stretches short-term costs over decades.
- Opening new credit before closing. A new card or car loan can change your rate or approval.
Run several scenarios in the refinance calculator above before you talk to lenders. Knowing your break-even month and interest trade-off puts you in control of the conversation.
Helpful resources: For more on refinance calculator, see the Consumer Financial Protection Bureau and U.S. Department of Housing and Urban Development.
Refinance calculator: frequently asked questions
When is it worth it to refinance a mortgage?
When the monthly savings repay your closing costs before you plan to move, and the new loan does not add too many years or too much total interest. Lowering your rate by about 0.75 to 1 point or more often makes sense, but run the break-even math.
How much does it cost to refinance?
Usually about 2% to 5% of the loan amount, including lender fees, appraisal, title and recording costs.
How do I calculate the break-even point?
Divide total refinance closing costs by your monthly savings. For example, $6,000 in costs and $300 a month in savings breaks even in 20 months.
Does refinancing restart my loan?
Yes, a refinance is a new loan. Choosing the same long term again can increase total interest even if your payment drops.
Is it worth refinancing to save $200 a month?
Often, yes, if you will stay long enough. With $6,000 in closing costs, saving $200 a month breaks even in 30 months. If you plan to stay well past that and do not add many years to the loan, the refinance usually pays off.
How much lower should my rate be to refinance?
There is no single rule, but in our $300,000 example, a half-point drop took about 42 months to break even, while a full point took about 25 months. Use the calculator with your real costs and how long you plan to stay.
Sources: Consumer Financial Protection Bureau, Freddie Mac, HUD. Prices are national planning ranges, not quotes. See how we research costs.
Latest Posts
 Best Boot Tray for Winter (2026): 8 Picks for Snowy, Muddy Entryways
 Best Watch Winder for Automatic Watches (2026): 7 Quiet Picks and a Gift Guide for Him
 Best Ice Ball Maker for Whiskey: 8 Clear Picks (2026 Gift Guide)
 Best Luxury Hair Perfume for Women: 8 Designer Hair Mists Worth Gifting (2026)
 Best Garment Racks With Covers (2026): Rolling, Heavy-Duty and Dust-Proof Clothes Racks
 Best Tennis Bracelets on Amazon (2026): CZ, Moissanite and Lab-Grown Diamond Gifts for Her